UK VAT set up in RamBase
For VAT purposes, the most important date is 1 January 2021, because that’s when:
EU VAT reporting rules changed. Trade with the EU became imports and exports
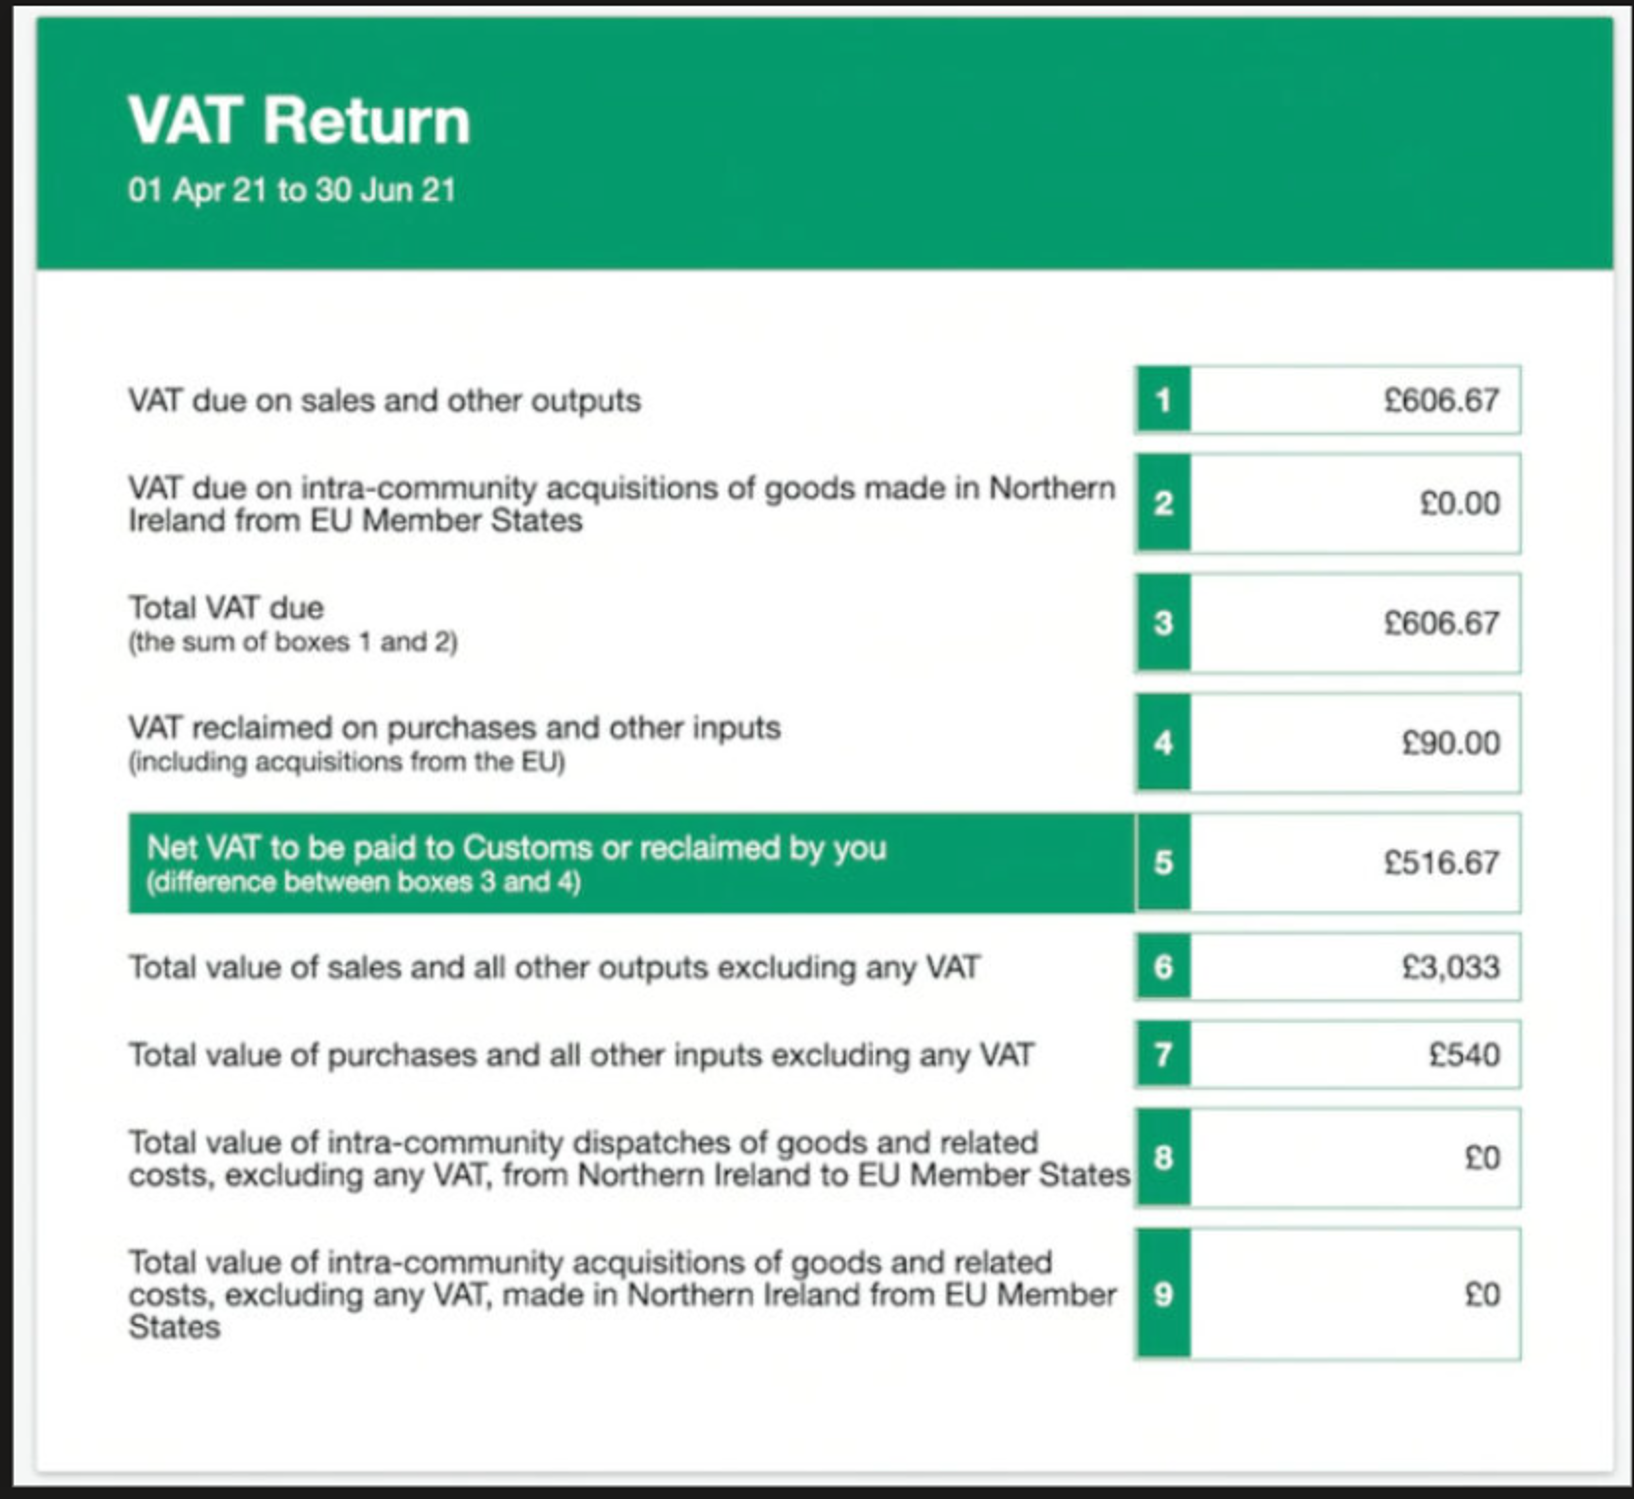
Boxes 2, 8, and 9 became mostly irrelevant for GB businesses. Boxes 2, 8 and 9 are now only relevant for Northern Ireland (goods trade with EU).
Imports/exports replaced EU “acquisitions/supplies” for UK (except for Northern Ireland).
Purchase of goods – Domestic within UK
Purchase of goods within Great Britain or Northen Ireland. Use VAT code 15, 16, 17 or 18. Sale will show in Box 7 (Net value) and VAT in box 4 (reclaim - ingoing VAT).
Purchase of services – Domestic within UK
Purchase of services within Great Britain or Northen Ireland. Use VAT code 23, 24, 25 or 26. Sale will show in Box 7 (Net value) and VAT in box 4 (reclaim - ingoing VAT).
Import of goods - UK
Goods imported (regardless of if from an EU county or from a non-EU country) to the UK - use Postponed VAT accounting (PVA).
Add VATREF=EUPURC to VATcode 56. VATcode 56 will then have VATREF=EXPPURC and EUPURC. Use VAT code 56 (standard rate), 57 (reduced rate), 54 (zero rate) or 55 (exempt). Purchase show in box 7 (Net value). Postponed VAT accounting, repost to VAT code 52 (standard rate) or 53 (reduced rate). Purchase show in box 7 (Net value) and VAT in box 1 (import – outgoing VAT) and 4 (reclaim – ingoing VAT).
ctivate VATcode 52 and 53 where we set up reverse charge.
Import of services - UK
Import of services (regardless of if from an EU country or from a non-EU country) to the UK – use VAT code 46 (standard rate) or 47 (reduced rate). Purchase show in box 6 (Net value) since import of services are subject to reversed charge. VAT in box 1 (import – outgoing VAT) and 4 (reclaim – ingoing VAT). Box 7 is purchased goods only.
Acquisition of goods – Northen Ireland
Goods supplied from an EU country to Northern Ireland are treated as an intra-EU acquisition of goods. Northern Ireland continues to follow EU VAT rules for goods after Brexit.
Goods imported to Northen Ireland from an EU country. Use VAT code 35 (standard rate), 36 (reduced rate) or 37 (zero rate). Purchase show in box 9 (Net value), box 7 (Net value), box 2 (VAT due to EU acquisitions – outgoing VAT) and box 4 (reclaim ingoing VAT).
Import of goods – Northern Ireland
Goods imported to Northen Ireland from a non-EU country. Use VAT code 56 (standard rate), 57 (reduced rate), 54 (zero rate) or 55 (exempt). Purchase show in box 7 (Net value). Postponed VAT accounting, repost to VAT code 52 (standard rate) or 53 (reduced rate). Purchase show in box 7 (Net value) and VAT in box 1(import – outgoing VAT) and 4 (reclaim – ingoing VAT).
Acquisition and import of services – Northen Ireland
Services received from EU or non-EU supplier to Northern Ireland. For acquisition (import) of services into Northern Ireland, the treatment follows the standard UK reverse charge rules — the same as for Great Britain.
Import of services to Northen Ireland from an EU country or a non-EU country. Use VAT code 46 (standard rate) or 47 (reduced rate). Purchase show in box 6 (Net value) since import of services are subject to reversed charge. VAT in box 1(import – outgoing VAT) and 4 (reclaim – ingoing VAT). Box 7 is purchased goods only.
Sales of goods – Domestic within UK
Sale of goods sold within Great Britain or Northen Ireland. Use VAT code 01, 02, 03 or 04. Sale will show in Box 6 (Net value) and VAT in box 1 (outgoing VAT).
Export of goods - UK
Sale of goods sold to an EU country or to a non-EU country. We move VATREF=EUSALE from VAT code 30 to VAT code 40. Use VAT code 40. Sale will show in Box 6. No VAT.
Sales of services – Domestic within UK
Sale of services sold within Great Britain or Northen Ireland. Use VAT code 08, 09, 10 or 11. Sale will show in Box 6 (Net value) and VAT in box 1 (outgoing VAT).
Export of services - UK
Sale of services sold to an EU country or to a non-EU country. Use VAT code 41 (zero rate) or 42 (exempt rate). Sale will show in Box 6. No VAT.
Dispatches of goods– Northern Ireland
Sale of goods sold to an EU country. Use VAT code 30. Sale will show in box 6 (Net value) and box 8 (Net amount).
Export of goods– Northern Ireland
Sale of goods sold to a non-EU country. Use VAT code 40. Sale will show in Box 6. No VAT.
Export of services – Northern Ireland
Sale of services sold to an EU country or to a non-EU country. Use VAT code 41 (zero rate) or 42 (exempt rate). Sale will show in Box 6. No VAT. Box 8 is not used for services (even to EU customers).
UK VAT return
The current VAT return will be valid in RamBase to and including VATPERIOD:202601. (Internal: SCV/72787) The updated VAT return will be valid in RamBase from VATPERIOD:202602. (Internal: SCV/84060)